[AINews] Anthropic files for $2T IPO in 2 weeks: 1400% growth rate, 48% of revenue through cloud partners, 85% margin, $1B op profit in Q2, $134B cash in bank and $10B lifetime burn
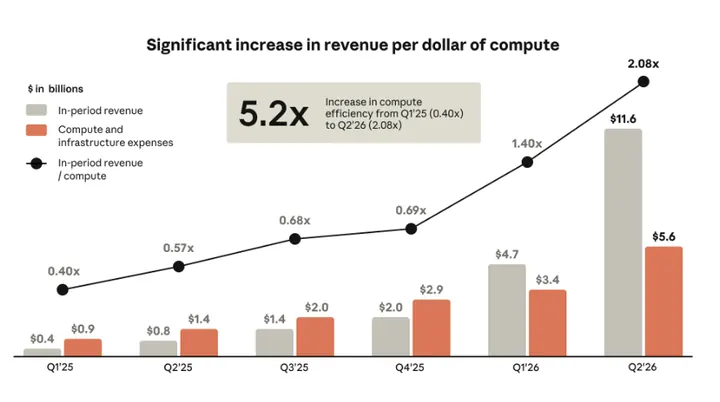
Today is one of those days that is tougher to cover for a normally-engineer audience that isn’t used to reading most S-1’s, let alone 350 pages of one of the most unusual S-1’s of all time : Better visualized: With significant operating leverage causing the first profitable quarter in Anthropic history (adjusted for $1B/quarter of SBC): The incredible efficiency story is told in two loops, and of course you know, we love loop: The pitch going forward is “virtual collaborators” (don’t say agent!) for over a billion knowledge workers by 2028: We believe we have reached an inflection point where AI systems can function as genuine collaborators in professional work. They quickly complete substantive tasks that might otherwise occupy a skilled professional for several hours, a full day, or longer. AI systems are also becoming increasingly capable of performing tasks that were previously too difficult or costly to complete or surfacing original insights and analyses. We refer to these AI systems that work alongside humans to perform complex, multi-step work at professional levels as Virtual Collaborators. Virtual Collaborators carry the access rights, system connections, and context that their organizations grant them , which allows them to function more accurately and reliably. They can navigate and use internal tools and execute workflows that span multiple steps that require sustained reasoning. Virtual Collaborators are AI designed to be embedded where work gets done, and our aim is to continue extending them to knowledge workers globally, a population that is estimated to exceed one billion in 2028. And we end with a useful map of all of Anthropic’s offerings on one screen: AI Twitter Recap Top Story: Anthropic files its S-1. Reactions and highlights What happened Anthropic publicly filed its S-1 on Monday at ~9am ET. It plans to list on Nasdaq under the ticker "ANT," and the filing shows a company that has crossed into operating profitability while carrying enormous compute commitments. Lead-up. Timing was reported by The Information ( @kimmonismus ), Fox Business ( @negligible_cap ) and Bloomberg ( @kimmonismus ). The IPO itself had been expected around Nov 9 ( @kimmonismus ). Official filing. Anthropic announced the filing with the standard registration disclaimer ( @AnthropicAI ). The EDGAR link was posted by @rishdotblog , and the ticker was flagged by @kimmonismus . Revenue. Revenue went from $41M in 2023 to $16.3B in H1 2026, roughly 14x year over year. Q2 alone was $11.6B, up 1,368% YoY ( @futurenomics , @kimmonismus ). Profitability. Q2 operating profit was $974M. H1 operating cash flow was +$3.9B. The headline $80.7B H1 net loss includes $81.1B of non-cash charges tied to financial instruments ( @kimmonismus ). Capital efficiency. Anthropic has raised $141.1B in aggregate. It holds $112.4B in cash plus $19.3B in short-term investments. Implied lifetime burn is about $9.7B ( @SemiAnalysis_ ), which SemiAnalysis called "likely the most efficient scaling of a business in the history of capitalism." Compute commitments. Non-cancelable commitments run deep into the next decade ( @scaling01 ). They include up to $120.5B for NVIDIA-powered compute through SpaceXAI, under agreements extending into 2029 ( @kimmonismus ). Pre-training delay. Anthropic disclosed it recently delayed pre-training of a new frontier model ( @scaling01 ). Anchor investor. Altimeter said it will participate "majorly" in the IPO on top of its existing stake ( @altcap ). Key numbers (facts from the filing vs. derived estimates) Gross margin trajectory ( @jaminball ): 2023: 37% 2024: −95% 2025: 40% H1 2025: 12% H1 2026: 85% Jamin Ball's summary of the filing ( @jaminball ): Revenue growth above 1,000% YoY in the last quarter. 21% free-cash-flow margin over the last six months. Less than $10B burned in total to reach more than $16B in quarterly revenue. He also cited a $16.8B Q3 figure that has been widely reported but is not in the S-1 ( @jaminball ). Cash and burn figures don't agree across accounts. SemiAnalysis puts burn at $9.7B; Austen Allred puts it at $9.4B. Cash is quoted as ~$132B (futurenomics) or $134B "today" (Ball). Austen claims $6.7B of positive cumulative FCF from 2023 to June 2026 and $575M/month of current FCF ( @Austen ). That sits awkwardly next to a $9.4B lifetime burn, so treat derived cash-flow figures with caution. How the $141B raise breaks down ( @jaminball ): About $128.6B of preferred stock proceeds. $11.3B of convertible notes from Amazon and Google issued in 2023–2025. About $5B has converted. The remaining $6.2B of principal carries a $108.6B fair-value liability, because it converts at $2–5/share versus a ~$59 Series H price. The convertibles are effectively ~1.8B shares, not debt, and that mark-to-market drives most of the GAAP loss. Remaining pieces: ~$0.6B of SAFEs/common and ~$0.7B from pre-2023 rounds. Distribution through cloud marketplaces ( @Bensign , @saranormous ): 48% of H1 2026 revenue (about $7.8B) flowed through Bedrock, Vertex and Azure Marketplace, up from 11% in 2023. Marketplace fees sit in sales, marketing and partnerships, not cost of revenue. They therefore never touch the headline 85% gross margin. Channel-partner fees rose about $2.7B YoY. Bensign's read: hyperscalers get paid twice, once for the compute and again for distribution. Compute efficiency. Aymeric Roucher derives $2.08 of revenue per $1 of compute, which implies under one year of payback on compute ( @AymericRoucher ). Internal use of Claude ( @TheRundownAI ): Internal Claude usage passed monthly personnel costs (excluding stock pay) in April. Measured at list prices, that usage grew more than 250x between January and September 2026. Separately, State of AI data says Claude "led" 27% of Anthropic's R&D ( @thursdai_pod ). Lockup. It is a staggered drip lasting more than a year, not the usual 180-day cliff. Some holders can sell on day one, which should smooth float ( @saranormous ). Public Benefit Fund ( @thursdai_pod , @thursdai_pod ): 5% of shares go into the fund. The board can add up to 2% more each time the company's value rises 50%. Founders have pledged 80% of their equity. Dario's reply to critics: Mythos-class models were held back from February to June. The narrative claims in the filing As summarized by @kimmonismus : AI matching or exceeding leading human experts across most professional and scientific disciplines "within a few years." These systems would work autonomously for days or weeks and operate lab equipment and robots. A "country of geniuses in a data center." "Closing the loop": Claude runs experiments, generates training data and automates evals and safety audits. Over 90% of September codebase contributions were written by Claude. An early-stage, unvalidated molecular-machine discovery that could become a gene-editing tool. Compute remains the binding constraint for the foreseeable future. Sarah Guo's first-pass read ( @saranormous ): An inflection in operating profit. Heavy emphasis on bio and novel discovery. A mismatch between consumption-based revenue and long-term compute obligations. Limited shareholder influence. Roughly 20 pages of case studies starting around page 220 ( @saranormous ). Notable absences and contradictions Custom chips. Elie Bakouch found no mention of in-house chip development anywhere in the S-1 ( @eliebakouch ). Risk factors say competitors "may be better positioned... to vertically integrate... including through proprietary chip design." They also say Anthropic depends on third-party design houses for "certain custom accelerator platforms." He caveats that a chip team may still exist ( @eliebakouch ). This conflicts with Dylan Patel's claim the day before that Anthropic "has already begun developing its own custom chip" ( @jukan05 ). The pre-training delay. @teortaxesTex reads it as rational: "10T @ 100T tokens is a bit of a waste," and Vera Rubins will be pricier. He still expects the IPO capital to accelerat